Helix
I designed and built a research and paper-trading system in which a signal must clear provenance, backtest, risk and validation checks before it reaches a simulated trading loop, across US, China A-share and Hong Kong equities.
Its own deflated-Sharpe gate rejects the book shown here, and no absolute backtest returns are quoted: survivorship inflates them by about five points a year.
Read the Helix case →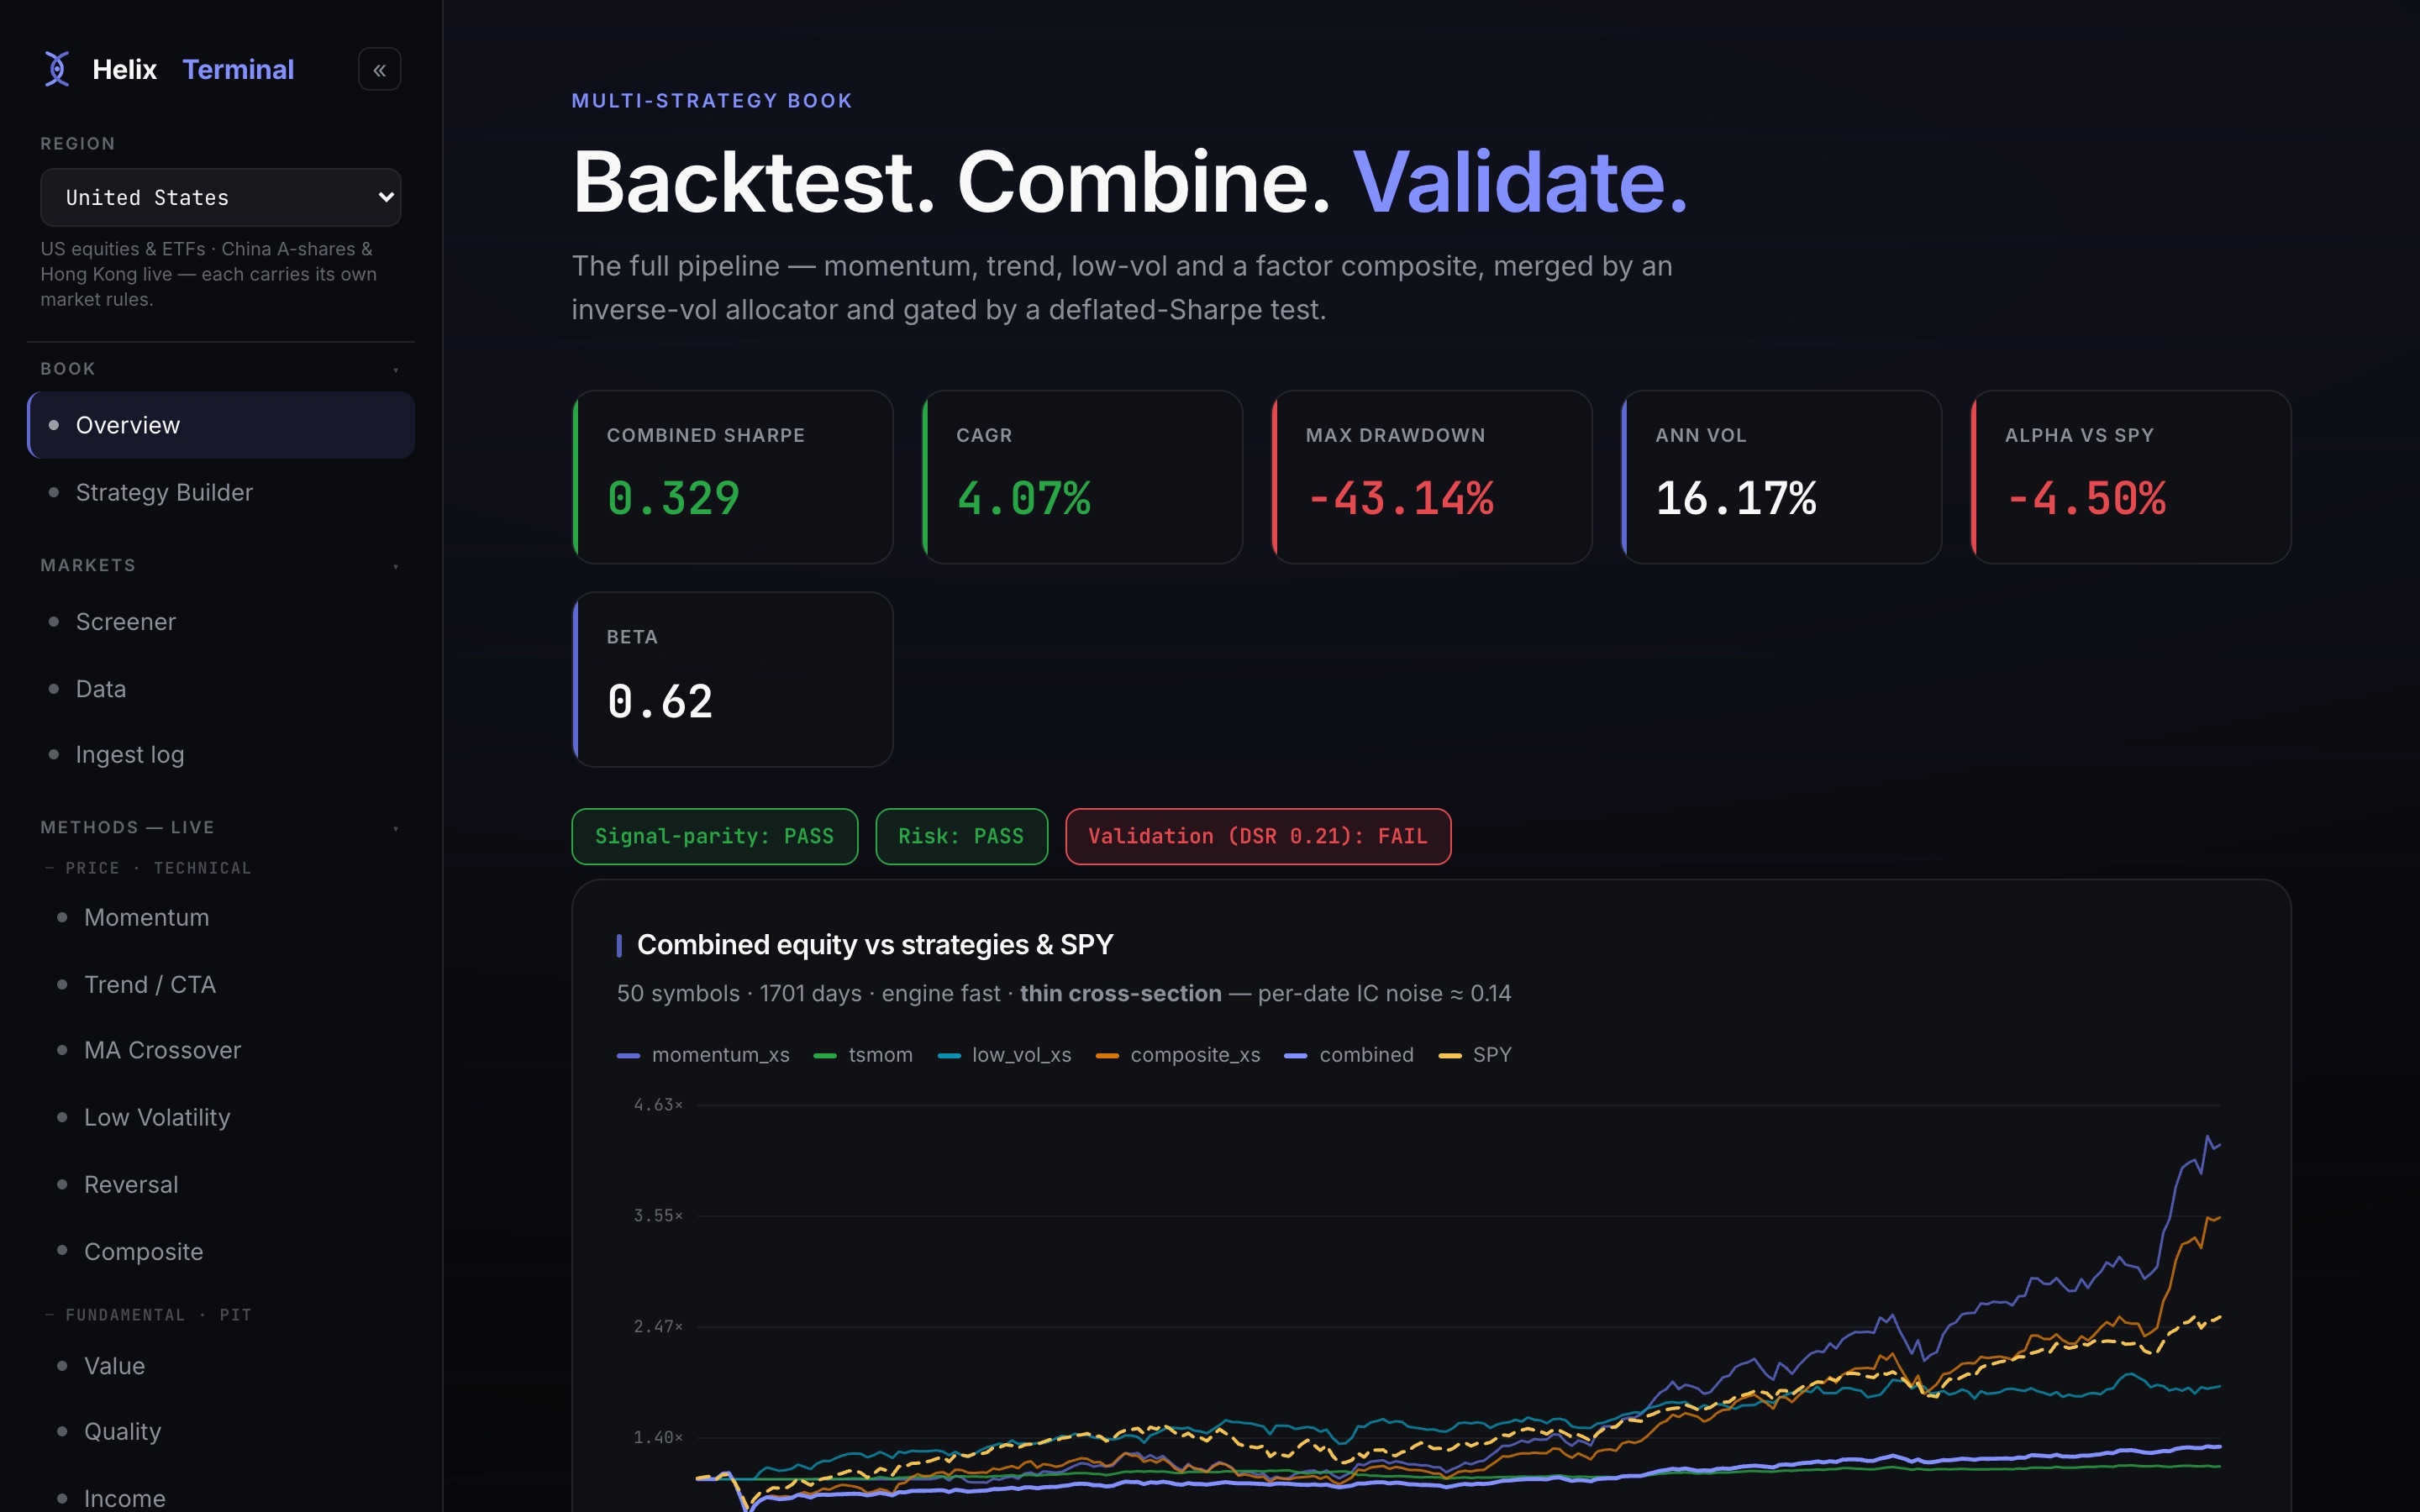
Validation gate · this snapshot
Signal parity · passRisk · passDeflated Sharpe 0.21 · fail
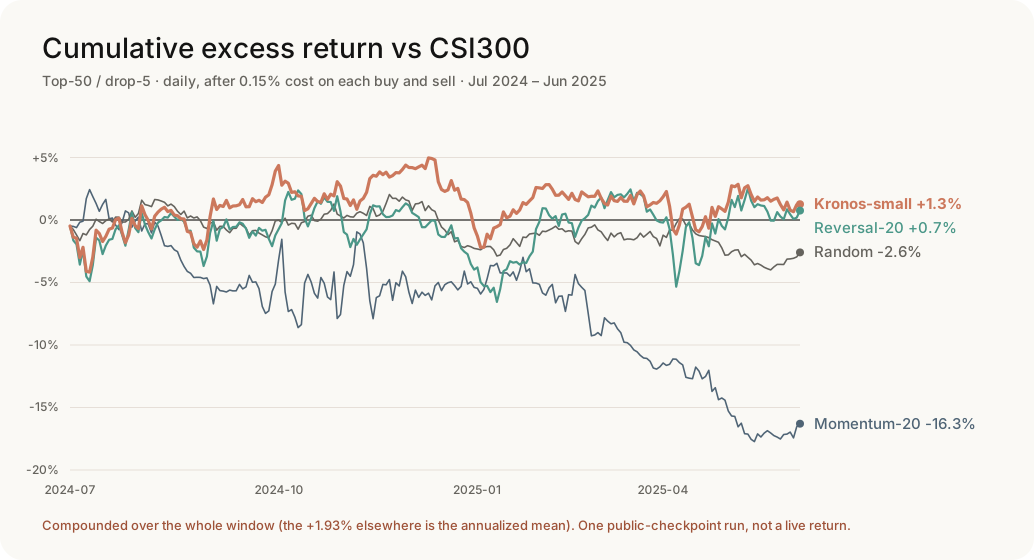
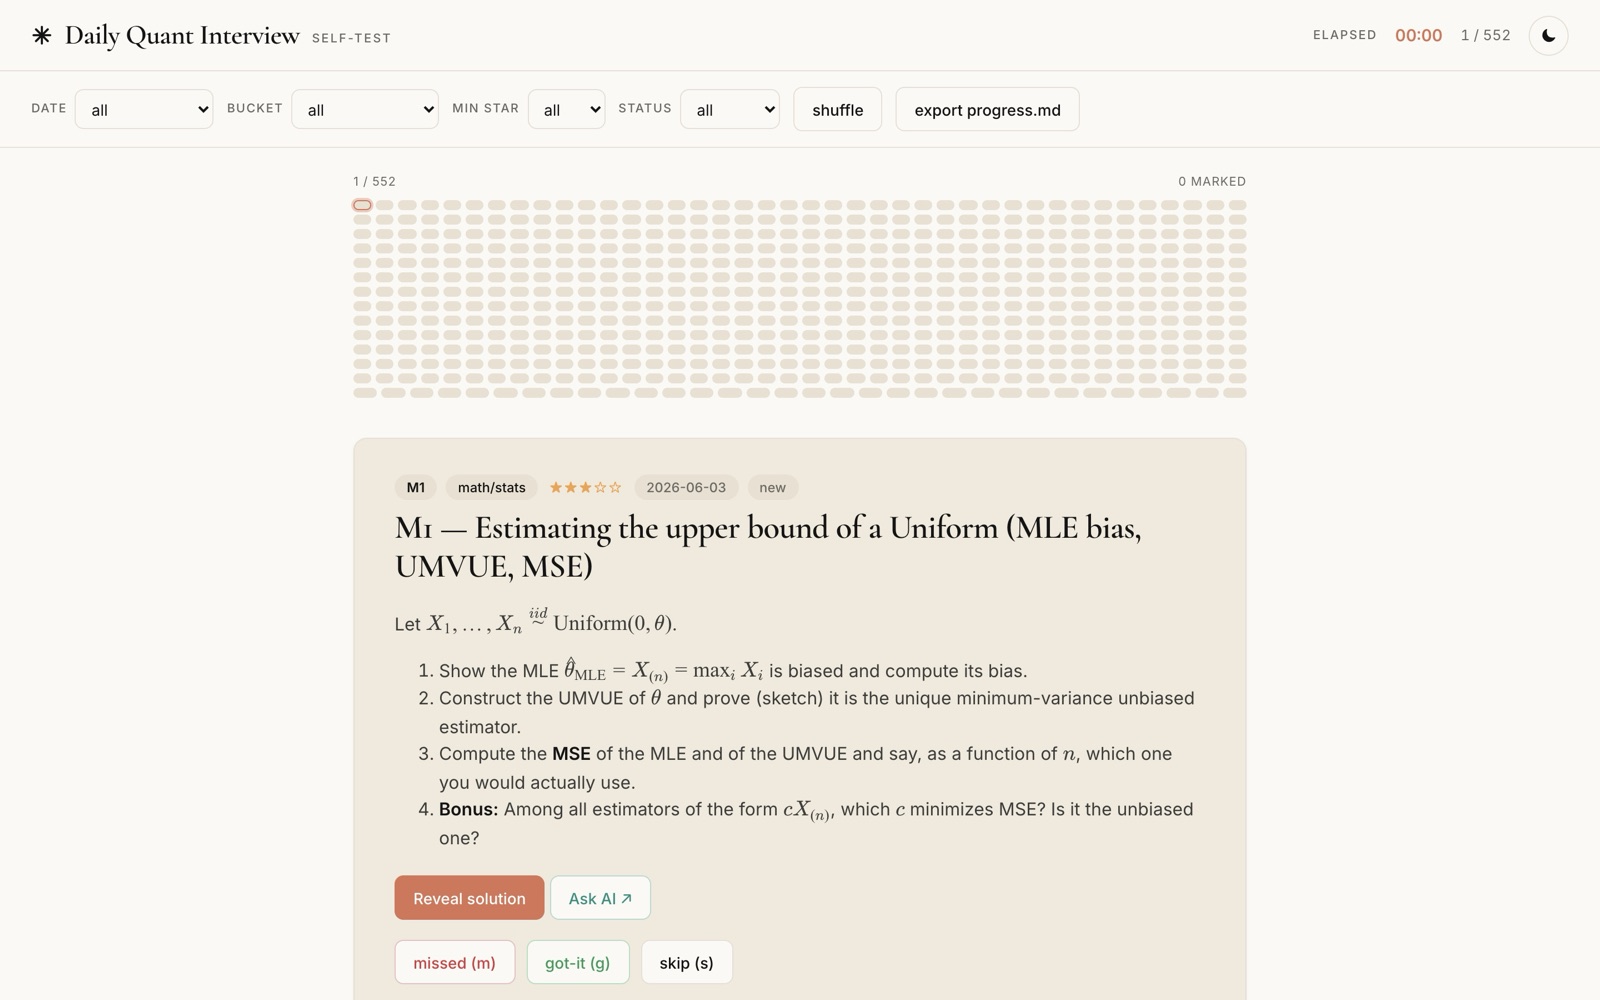
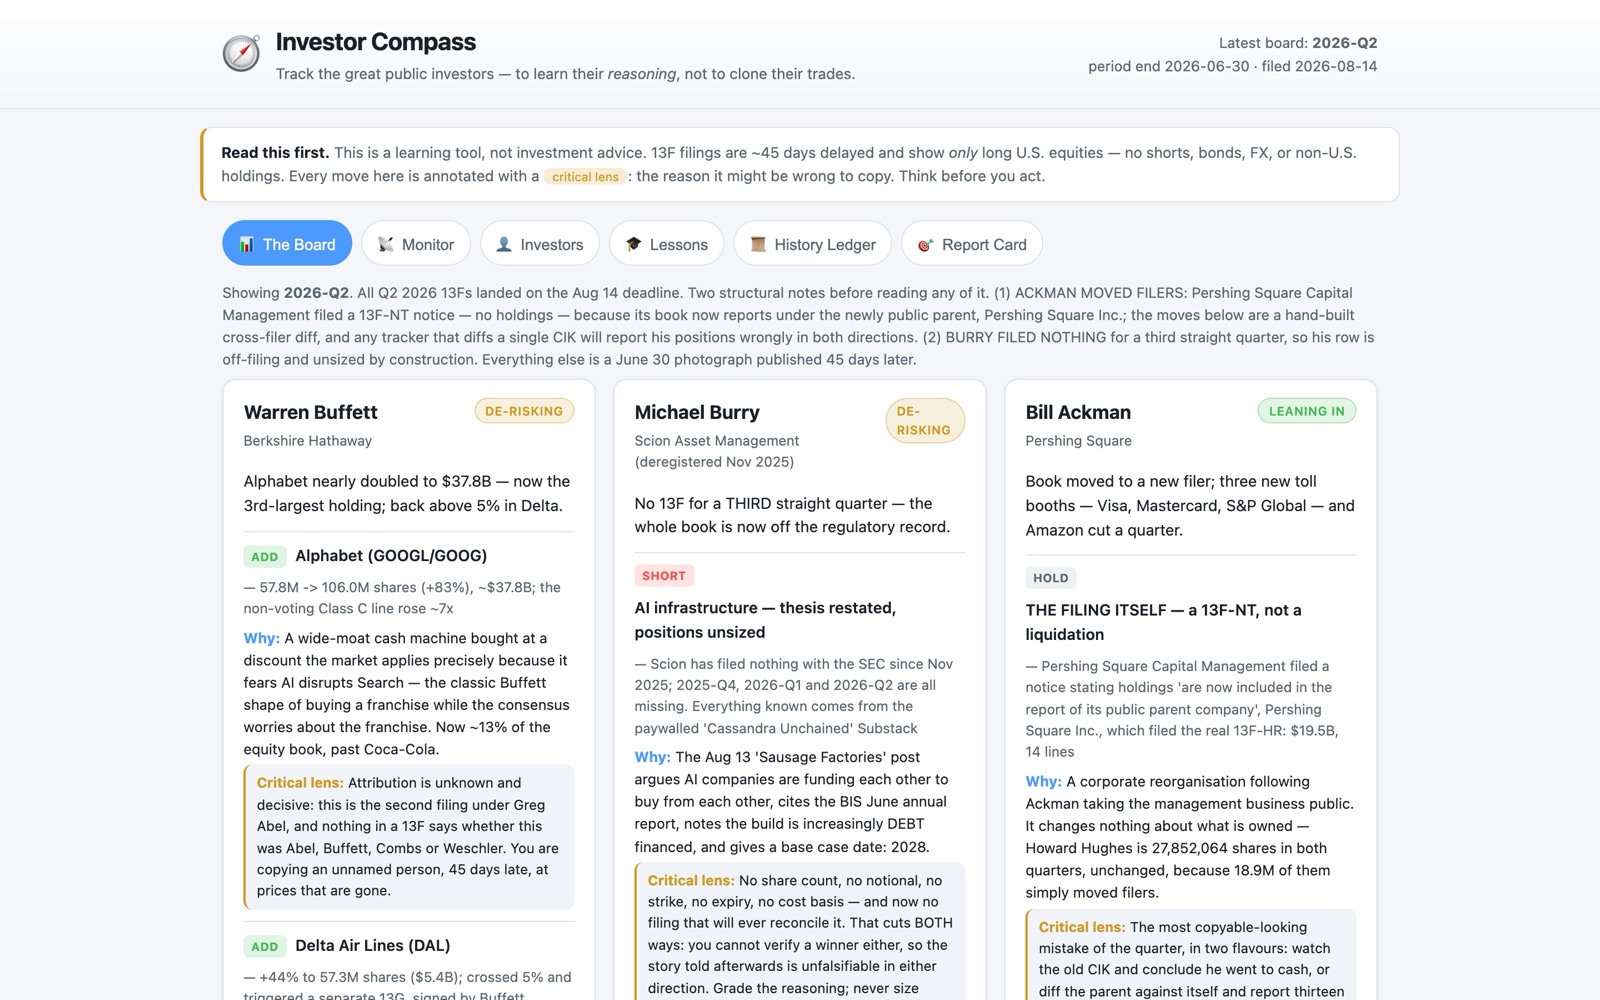
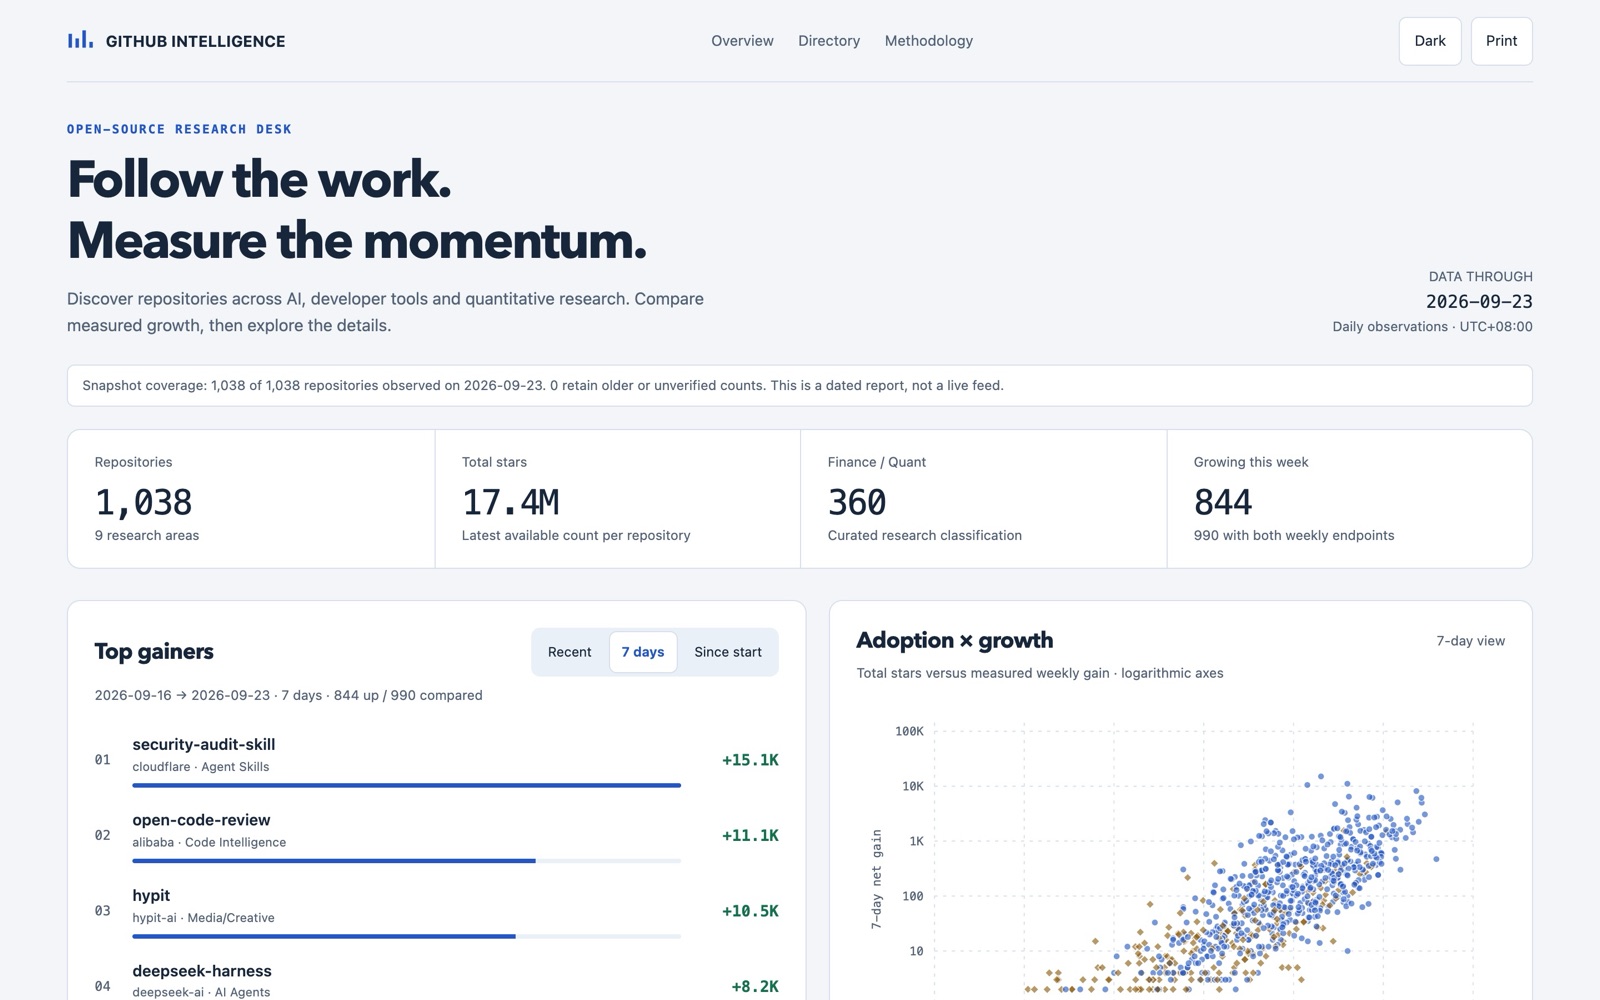
The system rejects its own book.Real screenshots of the Helix web front. The terminal shows a saved snapshot (27 Jul 2026, 50 liquid US stocks): an in-sample backtest whose combined book fails Helix’s own deflated-Sharpe gate. Its numbers are not performance claims.