A research system
with an audit trail.
Helix connects signal research, backtesting, portfolio controls, validation and paper trading, so each step can be inspected before a result reaches a decision.
- My role
- Design, implementation and validation
- Builds on
- Qlib (one ML sleeve); HKUDS Vibe-Trading factor engine (MIT)
- Since
- June 2026
- Markets
- US, China A-shares, Hong Kong
- Code
- Private repository
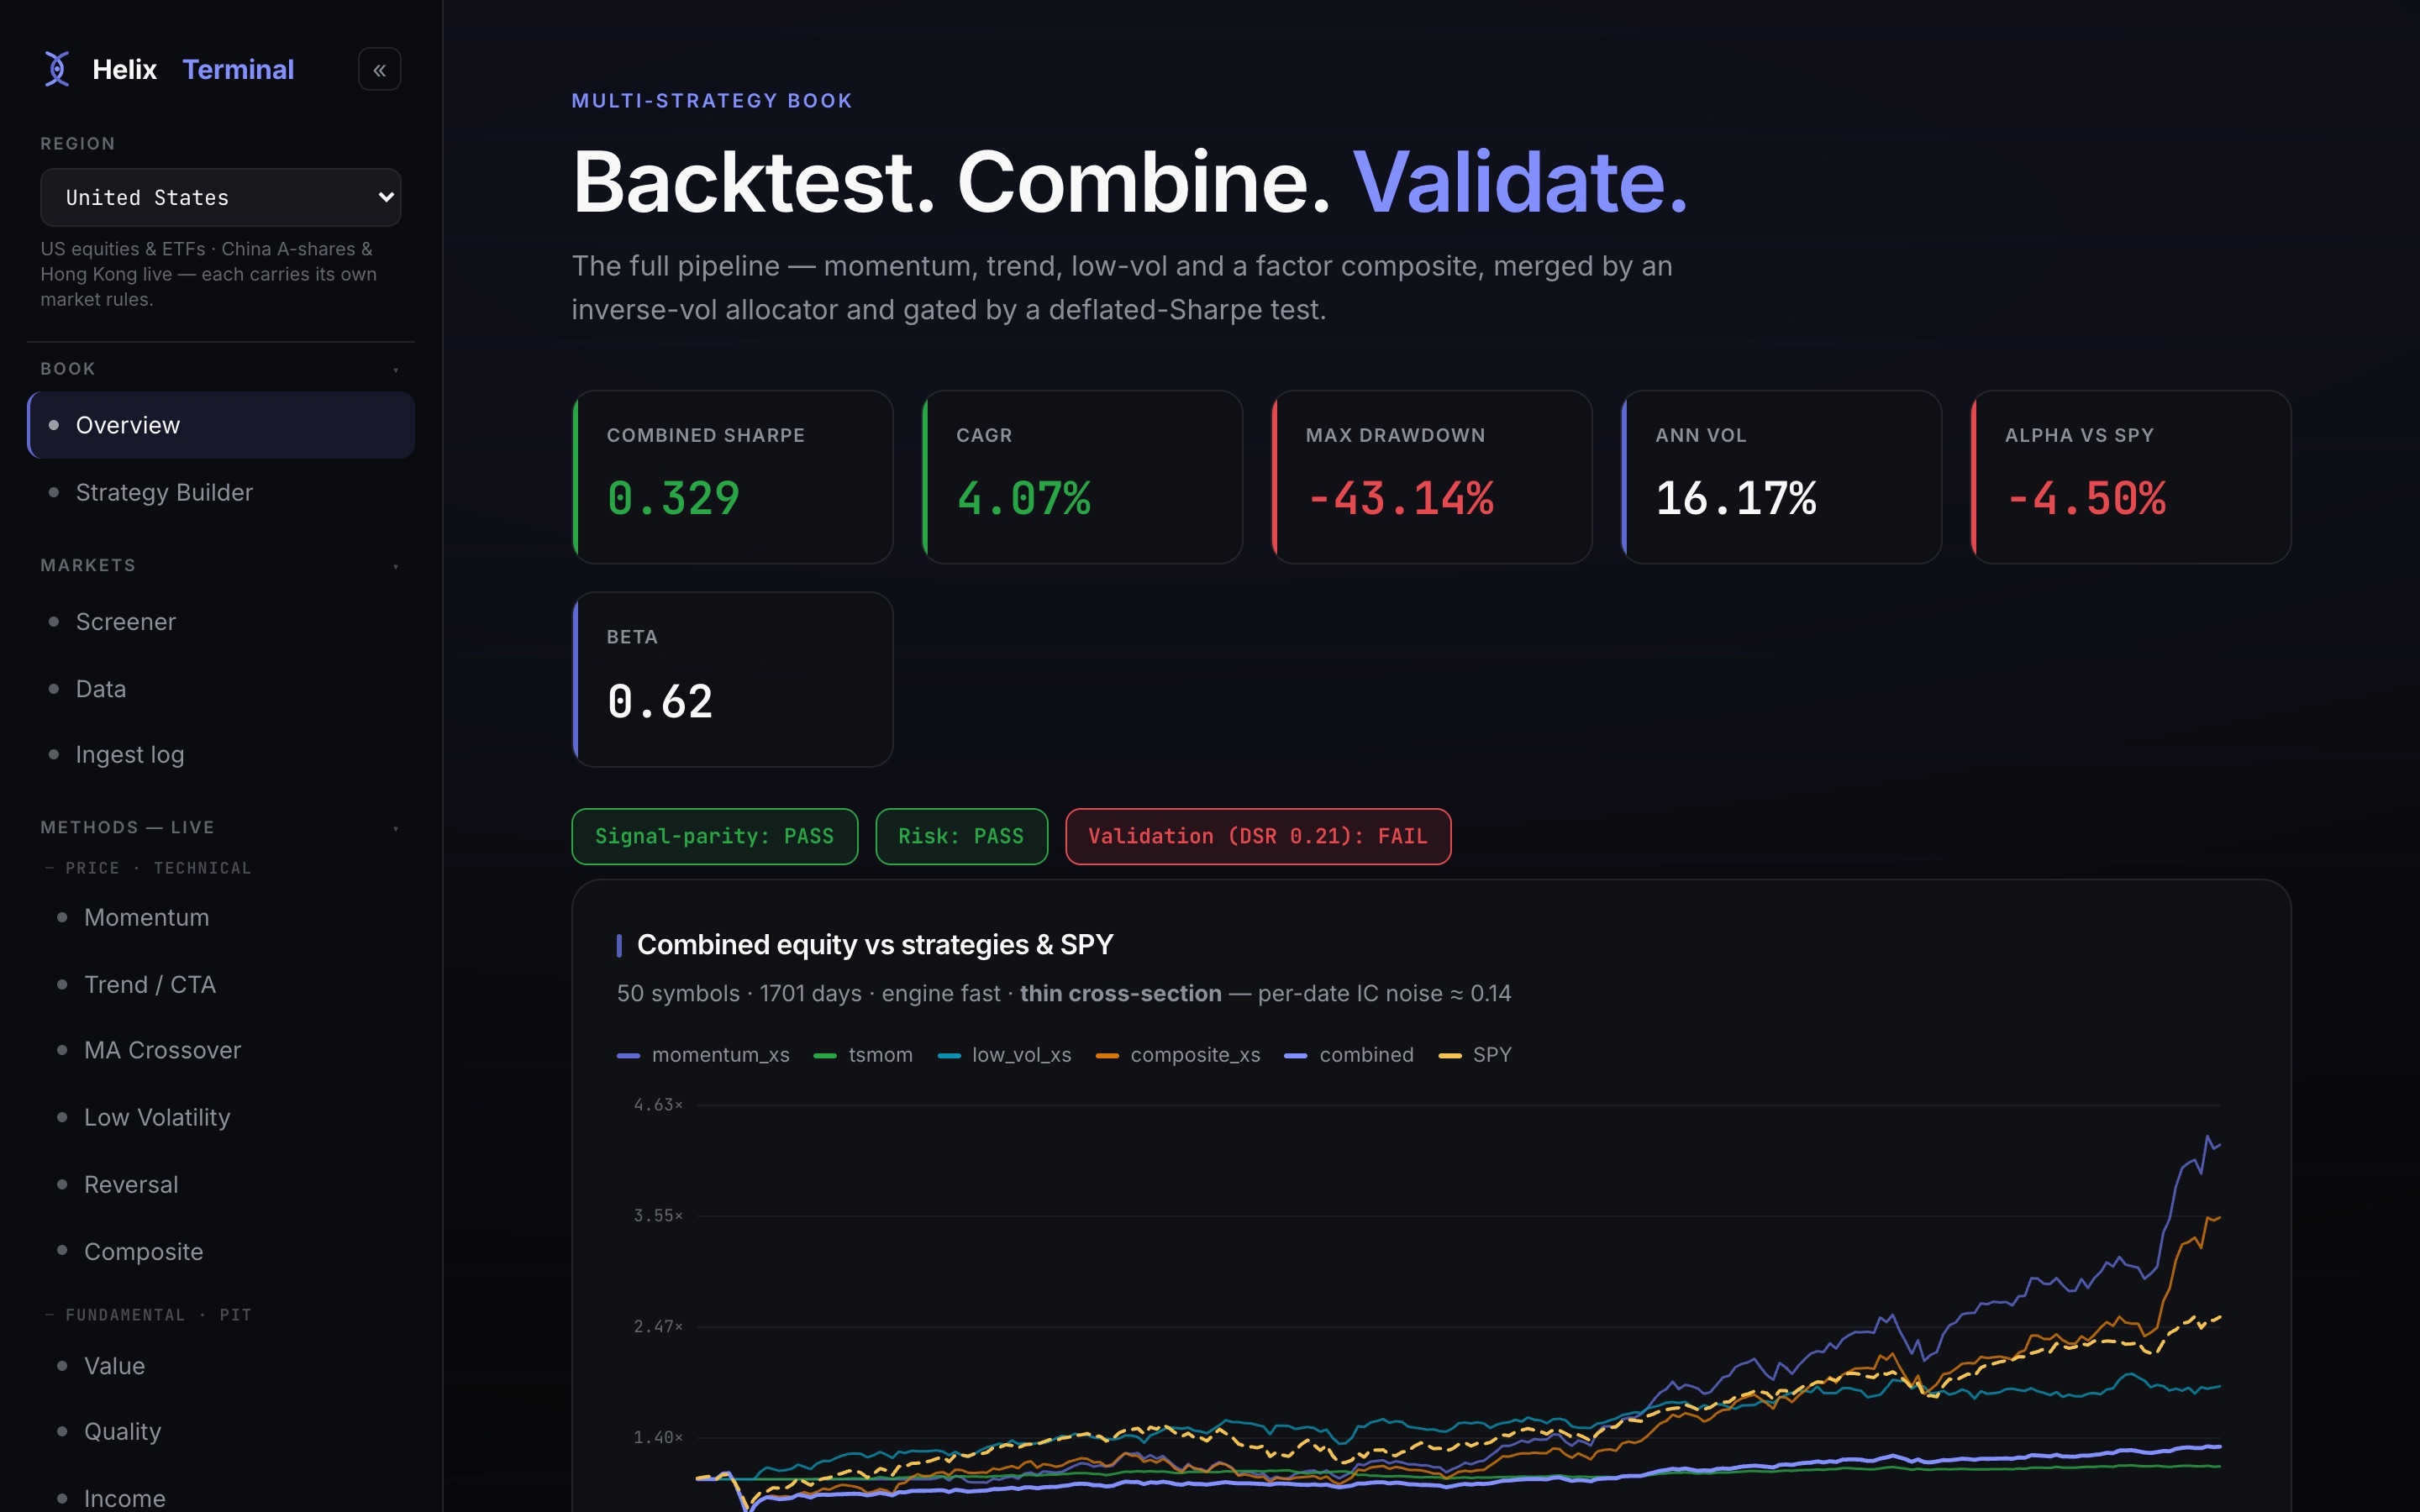
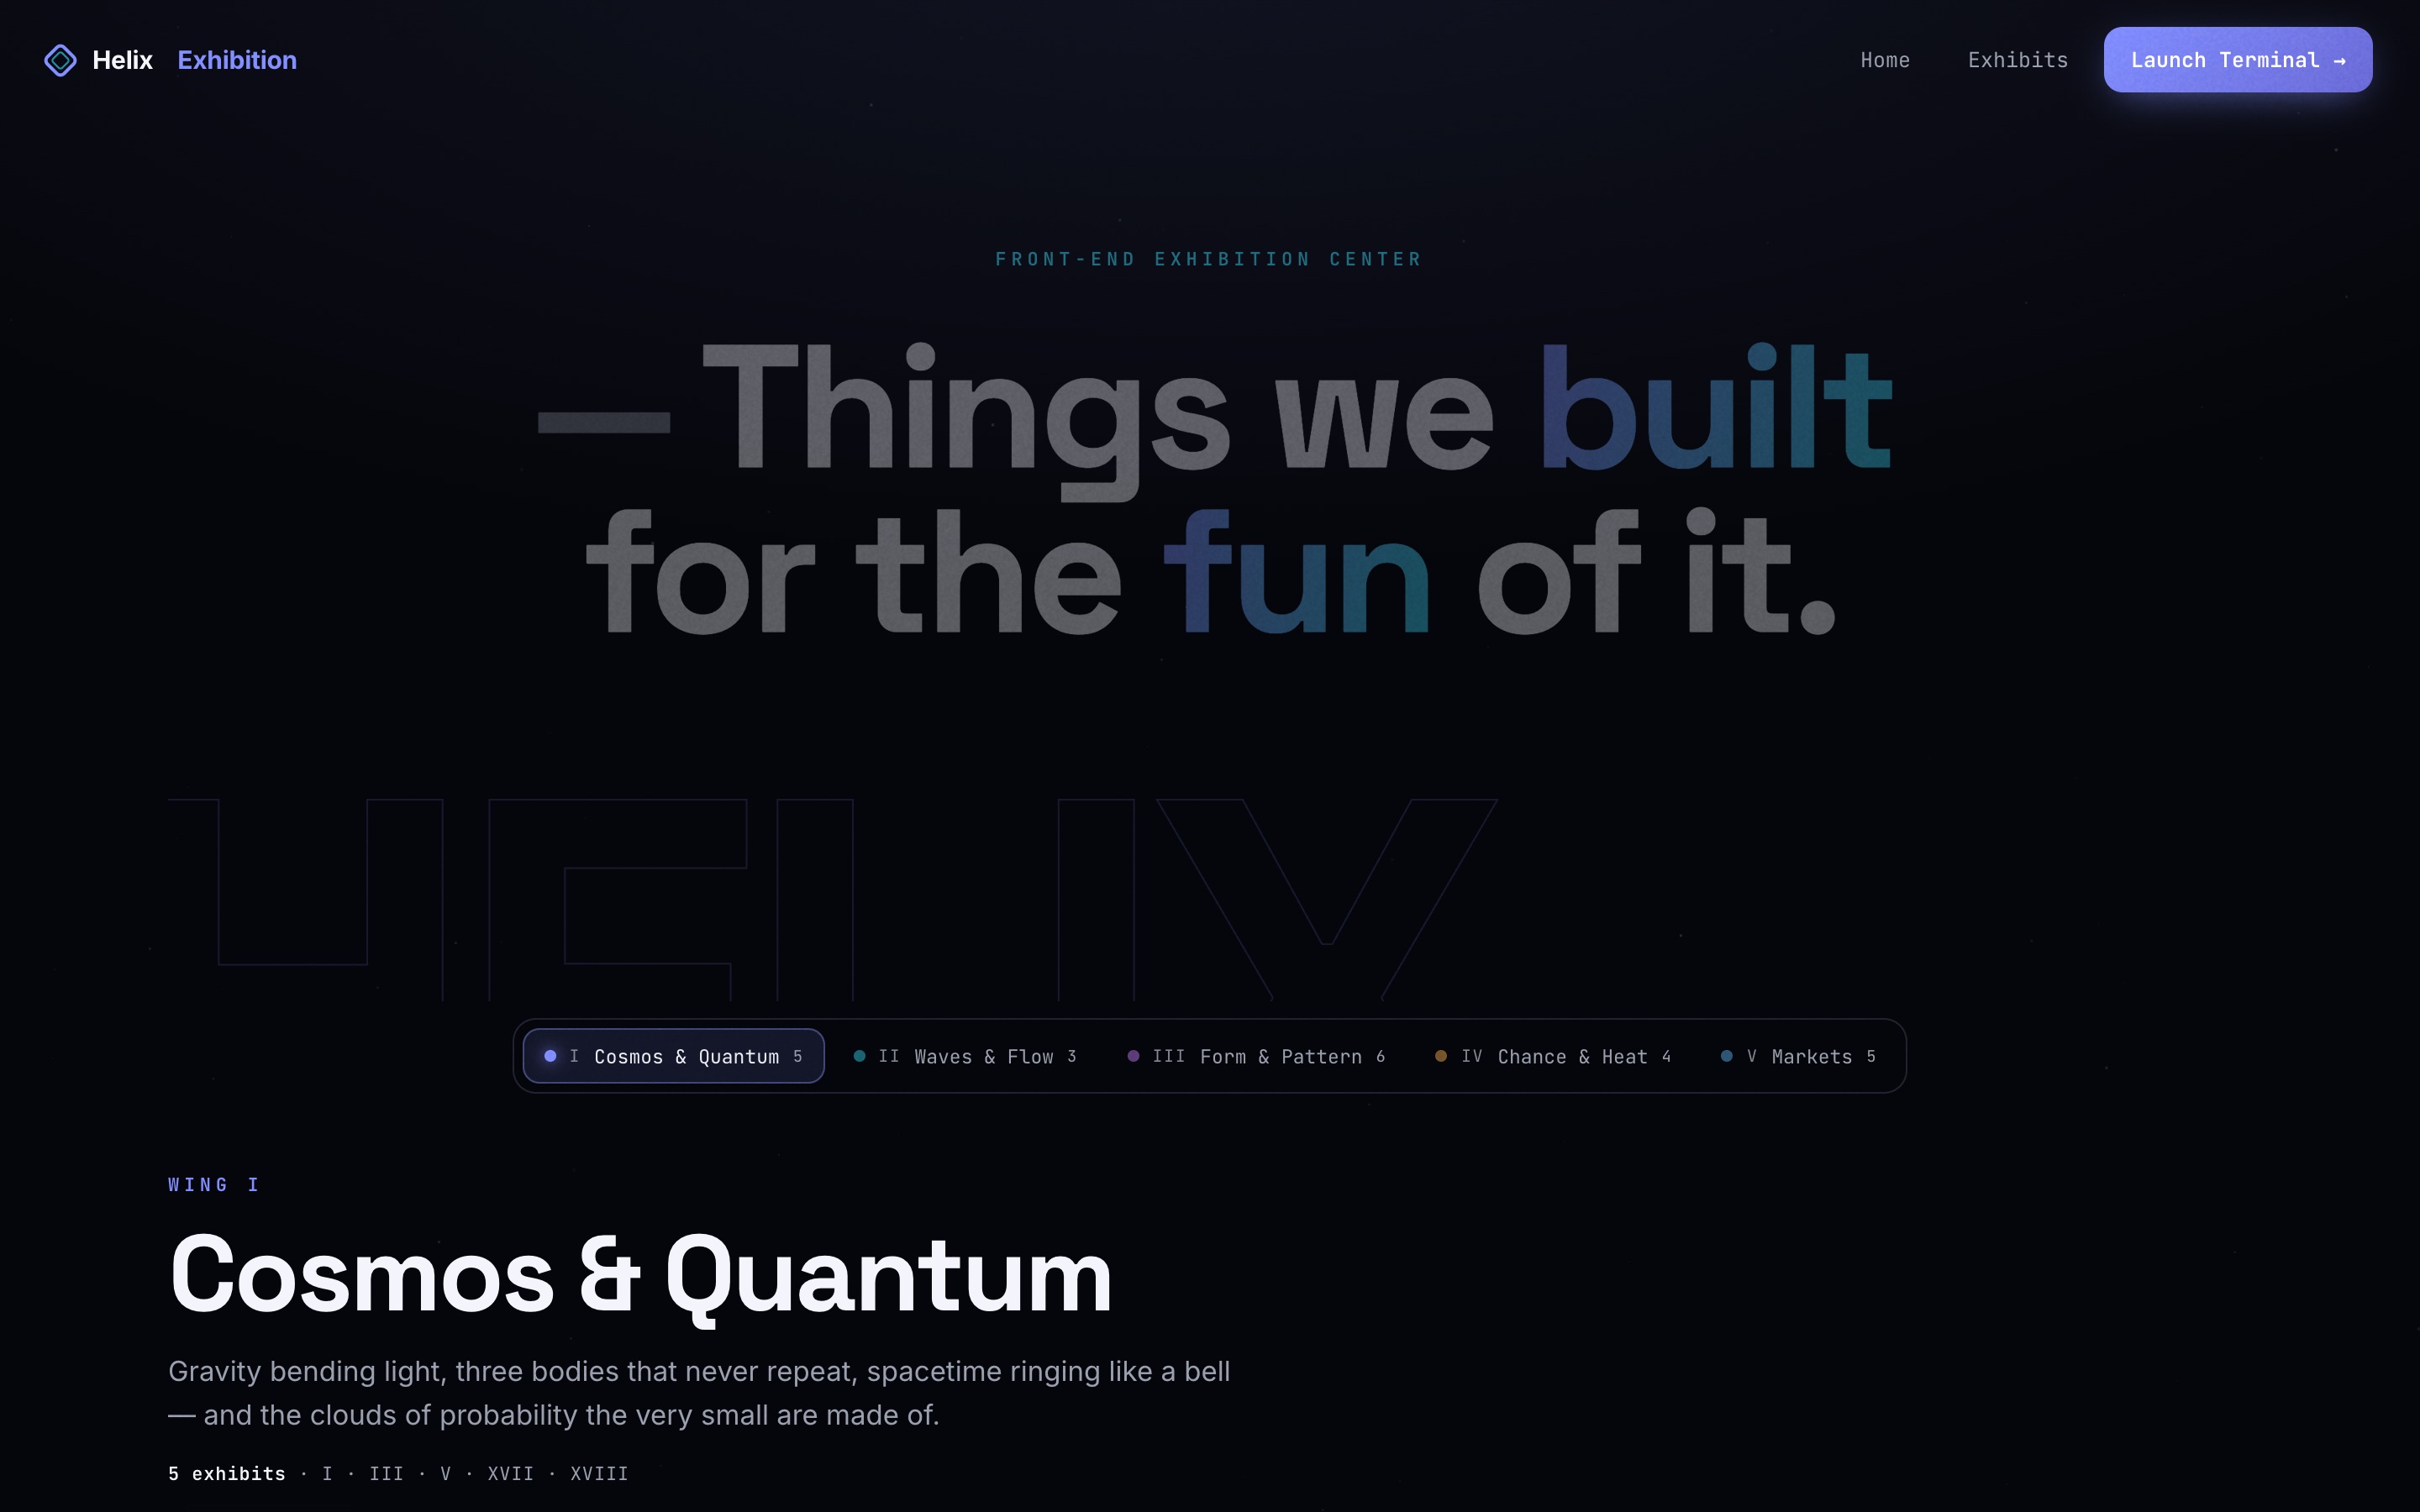
Real screenshots of the Helix web front. The terminal shows a saved snapshot (27 Jul 2026, 50 liquid US stocks): an in-sample backtest whose combined book fails Helix’s own deflated-Sharpe gate. Its numbers are not performance claims.
Can a signal stay traceable from research to paper execution?
A signal should carry its data provenance, a consistent backtest reading and risk checks before it reaches a paper workflow.
Built end to end, on others’ foundations.
I designed and built the shared signal core, factor lab, backtest engines, a risk-limited portfolio allocator, validation gates and the simulated paper-trading loop. Qlib powers one ML sleeve; the factor engine and factor library are vendored from HKUDS Vibe-Trading under the MIT licence.
Checks along the chain.
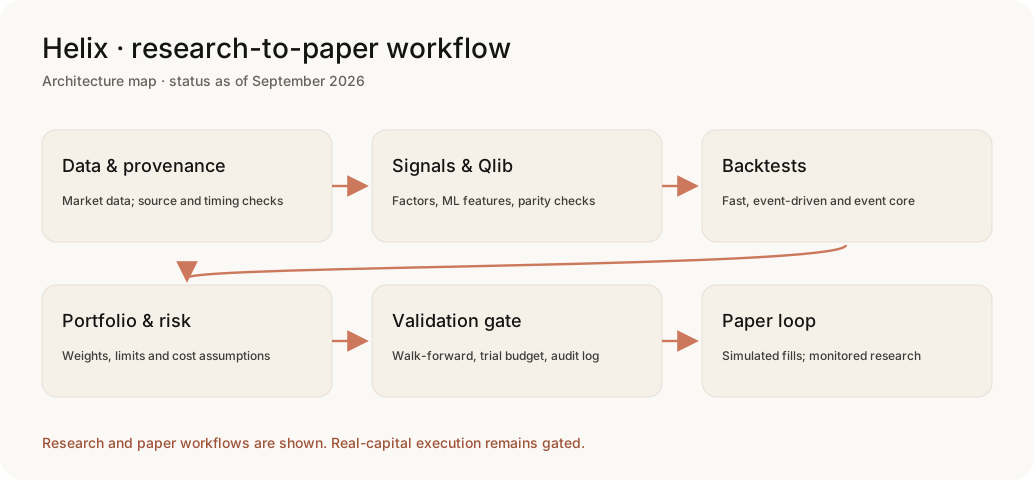
Signal parity checks, embargoed walk-forward research, cost-aware backtests and run records keyed by code, configuration and data. The map shows those components; it is not a performance chart.
Paper evidence has a boundary.
- Point-in-time universe masking is not routed through strategy backtests, so absolute returns are overstated by about five points a year; relative comparisons hold.
- Delisted price coverage is incomplete.
- The recorded paper history includes replayed days.
- Real-capital execution remains gated.